 California Construction Loans
 › Blog › How Construction Loan Draw Inspections and Milestone Payments Work in California
← All articlesHow Construction Loan Draw Inspections and Milestone Payments Work in California
Key takeaways
- Construction funds are normally released after a completed milestone, draw request, inspection, document review, and approval.
- A draw inspection verifies reported progress against the budget and schedule; it is not a universal certification of workmanship or code compliance.
- California progress payments use distinct statutory conditional and unconditional waiver-and-release forms.
- General-contractor releases do not prove that every subcontractor or supplier has been paid.
- Retainage, title updates, permits, Notice of Completion procedures, and final-completion documents can affect the timing of the last draw.
- Renovation products can use different escrow, reimbursement, initial-advance, inspection, and completion rules than ground-up construction loans.
- Draw delays can increase interest carry and create builder cash-flow pressure.
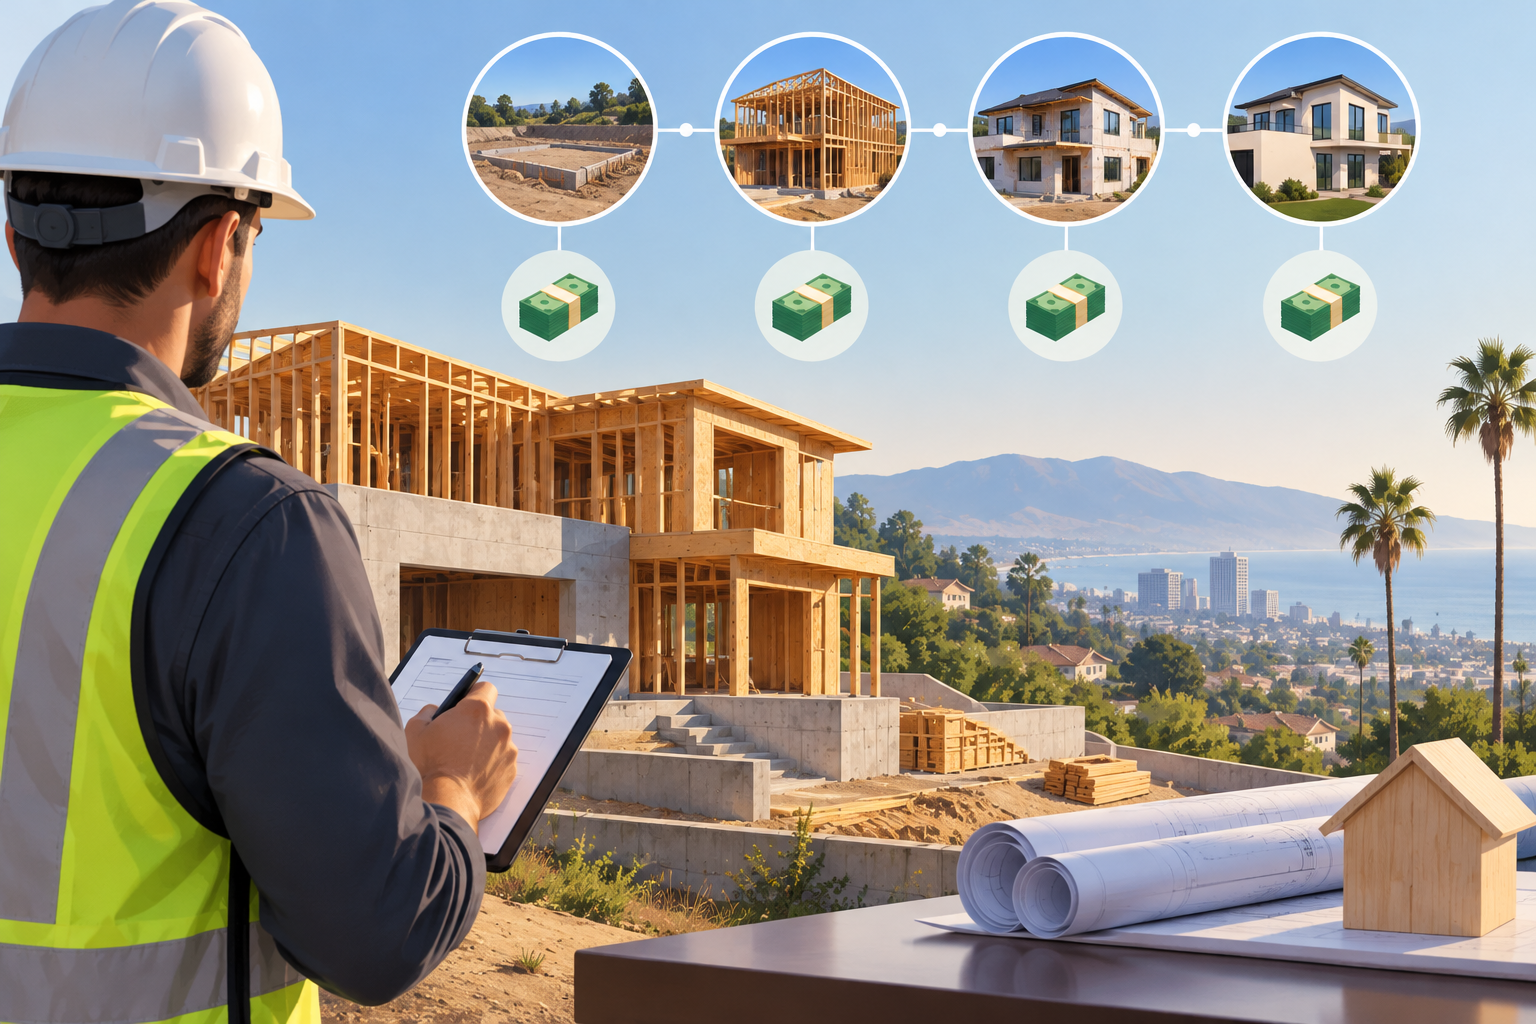
Construction loan funds are released through a controlled sequence: a construction milestone is completed, a draw request is submitted, an inspection verifies reported progress, the lender reviews the documents, and the approved amount is disbursed.
The lender does not normally advance the entire construction budget as unrestricted cash at closing. Instead, the loan documents establish a budget, schedule of values, draw procedure, payment recipients, inspection requirements, and any retainage or holdback.
How are construction loan funds released through draws?
Construction loan funds are released in scheduled draws that correspond to documented construction progress.
Before closing, the lender approves the project budget, plans, construction contract, schedule of values, and draw schedule. The schedule divides the work into measurable stages such as site preparation, foundation, framing, rough mechanical work, insulation and drywall, finishes, exterior completion, and final completion.
After a milestone is completed, the borrower or contractor submits a draw request identifying the work performed and the amount requested. The lender compares the request with the approved budget, prior disbursements, invoices, change orders, permits, lien documentation, and inspection results. The lender then releases the amount supported by the completed work and required documents.
This process protects the remaining loan proceeds, limits advances for unfinished work, and creates a payment record for the project.
Lender-specific variations
Lender procedures determine who must submit the draw, who receives the funds, whether the payment is made by wire, check, escrow disbursement, or joint check, when the inspection occurs, whether an initial advance is permitted, which documents are required, and how inspection fees are charged. The signed loan documents and construction escrow instructions control those details.
What does a construction draw inspection verify?
A construction draw inspection generally verifies that the reported physical progress is consistent with the requested draw, approved budget, and milestone schedule.
The inspector typically reviews visible progress at the property and reports whether the project has reached the stage associated with the draw. A framing draw may require substantially completed framing, while a rough-mechanical draw may require installed plumbing, electrical, or HVAC work within the requested scope.
A draw inspection is a progress and collateral-control review. It does not automatically certify workmanship, code compliance, architectural quality, contractor performance, or completion of every project item. Building-department inspections, permit records, architect or engineer certifications, appraisals, and final completion reports may serve separate purposes.
The lender may also review photographs, invoices, receipts, approved change orders, permit status, prior draw records, and evidence that earlier proceeds were used for the project. If the inspection shows less progress than the request claims, the lender may reduce the draw or defer payment until the work and documentation support the requested amount.
What is the usual construction loan draw sequence?
The usual draw sequence is milestone completion, draw submission, inspection, document review, approval, and disbursement.
1. Approve the budget and schedule. The lender approves the construction contract, plans, specifications, line-item budget, schedule of values, and draw schedule.
2. Complete a measurable milestone. The builder performs work corresponding to a budget category, such as grading, foundation, framing, rough-in, drywall, or finishes.
3. Submit the draw package. The borrower or contractor submits the lender’s draw form with progress details, invoices, photographs, receipts, approved change orders, permits, and required waiver-and-release documents.
4. Complete the inspection. A lender-selected inspector or other approved professional reviews the reported progress at the property.
5. Review the file. The lender checks the inspection report against the budget, prior draws, title requirements, permits, insurance, change orders, and lien documentation.
6. Approve or adjust the draw. The lender authorizes the supported amount, reduces the request, or identifies missing work or documents.
7. Release the funds. Payment is made to the party or parties identified in the loan documents, which may include the borrower, contractor, escrow holder, or joint payees.
A draw timeline can stretch when the inspection must be rescheduled, invoices do not match the budget, a change order lacks approval, a permit is missing, title has not been updated, or required lien waivers are incomplete.
Which construction milestones are commonly used for draw payments?
Construction draw milestones are based on visible, measurable stages that allow the lender to compare completed work with the approved budget.
Common custom-home milestones include:
- Site preparation and grading
- Foundation and footings
- Framing
- Roofing and exterior enclosure
- Rough plumbing, electrical, and HVAC
- Insulation and drywall
- Cabinets, flooring, fixtures, and interior finishes
- Exterior improvements and landscaping
- Final completion and certificate of occupancy, when required
A manufactured-home project may use separate milestones for site preparation, foundation work, delivery, installation, utility connections, and final completion. A land-and-construction transaction may fund the land component at closing and use a separate draw schedule for vertical construction.
No single California draw percentage applies to every milestone. The loan agreement, construction contract, approved budget, and schedule of values establish the amount assigned to each stage.
What should a California construction draw package include?
A complete draw package connects the requested payment to a specific completed milestone, budget category, and payment record.
A typical package may include:
- Lender draw request form
- Current schedule of values
- Contractor payment application
- Invoices and receipts
- Photographs of completed work
- Approved change orders
- Permit and inspection records
- Updated project schedule
- Contractor and subcontractor information
- Conditional waiver and release forms for the requested progress payment
- Unconditional waiver and release forms for prior payments
- Evidence of insurance when required
- Updated title information when required
The borrower should submit change orders before the related work is performed or billed. An unapproved change order can create a budget shortfall, delay the inspection, or cause the lender to exclude the cost from the draw.
How do California lien waivers and releases affect construction draws?
California progress draws commonly use the statutory waiver-and-release forms to document whether a claimant has been paid for a defined portion of the work.
For a progress payment that has not yet been received, the relevant form is the Conditional Waiver and Release Upon Progress Payment. It becomes effective upon the claimant’s receipt of payment, such as payment of the identified check or joint check.
After the claimant has received the progress payment, the relevant form is the Unconditional Waiver and Release Upon Progress Payment. It states that the claimant received the progress payment for the work and period identified in the form.
The progress-payment forms do not serve the same purpose as the final-payment forms. California also provides separate Conditional Waiver and Release Upon Final Payment and Unconditional Waiver and Release Upon Final Payment forms.
A release from the general contractor does not establish that every subcontractor, laborer, or material supplier has been paid. Owners and lenders commonly collect releases from the parties whose unpaid claims could affect the property or the lender’s lien position. Joint checks can provide additional payment control by naming the contractor and a subcontractor or supplier as joint payees.
A California owner or lender may use prior-payment unconditional releases as a payment-control condition for the next draw. California Civil Code Section 8800 establishes a private-work progress-payment rule for undisputed amounts after a qualifying payment demand and addresses withholding for a good-faith dispute; the statute also preserves separate retention requirements.
Retainage and draw holdbacks
Retainage is money withheld from an otherwise approved progress payment until a later project stage or final completion. A lender may also hold back funds for incomplete work, unresolved lien exposure, missing documents, unfinished punch-list items, or a required final title update.
Retainage affects builder cash flow because the contractor may incur labor, material, and subcontractor costs before receiving the full amount assigned to the completed milestone. The construction contract and loan documents should identify the applicable holdback and release conditions.
What is the effect of a California Notice of Completion?
A properly recorded California Notice of Completion can shorten the period in which certain contractors, subcontractors, laborers, and material suppliers may record a mechanics lien after project completion.
The notice is a post-completion title and lien-management step rather than a substitute for collecting progress-payment waivers. Owners should coordinate the notice with the project completion date, final payment, title requirements, and lender instructions because an inaccurate or premature filing can create problems for the project record.
How do draw amounts affect construction loan payments?
Construction-loan payments generally increase as approved draws increase the outstanding principal balance.
Interest-only construction structures commonly calculate construction-period interest on the amount advanced and outstanding rather than on the full loan commitment. Under that structure, early payments are usually lower because the project has drawn less principal, while later payments rise as foundation, framing, mechanical, and finish draws are funded.
The note and loan agreement control the interest calculation, payment schedule, reserve structure, and transition to permanent financing. A construction-to-permanent loan can move into a long-term mortgage phase after construction completion, but the construction-period draw rules still govern disbursements before conversion.
Draw delays can increase interest-carry pressure, extend the period during which the builder must finance labor and materials, and disrupt the project schedule. Borrowers should include inspection fees, retainage, contingency needs, and possible payment gaps in the construction budget.
What special rules apply to renovation draw funds?
Renovation financing uses lender-controlled escrow or reimbursement procedures, but renovation products can differ materially in their inspection, initial-advance, contractor-documentation, completion, and title-update requirements.
For Fannie Mae HomeStyle Refresh, the lender may fund up to 50% of planned renovation costs at closing as an initial draw, and the improvements must be completed within 180 days of the mortgage note date. Remaining funds stay under renovation controls until the lender’s requirements are satisfied.
For eligible Fannie Mae renovation transactions, the final disbursement can require completion certification, an appraisal or completion report, a certificate of occupancy when required by local authorities, updated insurance evidence, and a title update through the completion date. The final title review is used to protect first-lien priority and address outstanding mechanics’ or materialmen’s liens.
Certain Fannie Mae postponed-improvement escrows require funds equal to 120% of estimated completion cost, while a guaranteed fixed-price completion contract can permit an escrow equal to the full contract price under the applicable program rules.
Renovation draw example
A borrower completing a kitchen and structural remodel may submit a first request after demolition and structural work, a second request after rough plumbing and electrical work, a third request after cabinets and drywall, and a final request after finishes, inspections, completion documentation, and title requirements are satisfied.
The lender may reimburse completed work, release escrowed funds directly to the contractor, issue joint checks, or use another procedure established by the renovation program and loan documents. A renovation loan should not be treated as identical to a ground-up construction loan merely because both use staged funding.
Why is a construction draw rejected or reduced?
A construction draw is rejected or reduced when the inspection, budget, title record, permits, payment documentation, or lien documentation does not support the amount requested.
Common reasons include:
- The requested work is incomplete or not visible
- The draw exceeds the approved budget category
- The lender has not approved a change order
- Invoices do not match the schedule of values
- Required permits or building inspections are missing
- Prior draw proceeds cannot be reconciled
- Conditional or unconditional waivers are missing or inaccurate
- A title update identifies a lien or another priority issue
- The project is behind schedule or materially different from the approved plans
- Required insurance, completion, or occupancy documents are absent
The practical response is to obtain the lender’s written deficiency list, correct the construction or documentation issue, and resubmit the supported amount rather than repeatedly requesting the full original draw.
How should borrowers prepare before closing?
Borrowers should understand the draw schedule, inspection process, payment recipients, waiver requirements, retainage, fees, title updates, and final-completion conditions before signing the construction loan.
Before closing, confirm:
- Who submits each draw
- Who schedules and pays for inspections
- The expected inspection-to-funding timeline
- Whether an initial advance is permitted
- Whether funds go to the borrower, contractor, escrow holder, or joint payees
- Which invoices, receipts, photographs, permits, and waivers are required
- How approved change orders affect the budget
- What retainage or holdback applies
- How title updates and lien releases are handled
- What documents trigger final disbursement
- How construction-period interest and reserves are calculated
A realistic budget, organized records, an approved change-order process, and advance coordination with the lender reduce avoidable draw delays.
Frequently asked questions
How long does a construction loan draw take after an inspection?
A draw is funded after the inspection, document review, and payment conditions are complete, with the actual timing established by the lender’s procedures and loan documents.
Should the borrower or contractor submit the draw request?
The borrower or contractor submits the draw request according to the lender’s written procedure, and the loan documents identify the responsible party.
What happens when a draw is rejected?
The lender identifies the missing work or documentation, and the borrower or contractor corrects the deficiency before resubmitting the supported amount.
Who pays construction inspection fees?
Inspection fees are charged according to the construction loan agreement, escrow instructions, or lender fee schedule.
Does retainage reduce every construction draw?
Retainage reduces a draw when the construction contract or loan documents authorize a holdback for later completion, punch-list work, or another stated condition.
Can a lender delay payment after the inspection is complete?
A lender can delay disbursement when required documents, title information, permits, lien releases, approvals, or other payment conditions remain incomplete.
Can a contractor receive funds before completing all work in a milestone?
A contractor receives a standard progress draw for the completed and documented portion supported by the inspection and loan documents, while an initial advance is available only when the applicable program and loan documents permit it.
Does every construction loan use the same draw process?
Every construction loan does not use the same draw process because lenders and renovation programs set different rules for inspections, reimbursements, escrow controls, payment recipients, documentation, and completion.
Do construction-loan payments rise during the build?
Construction-loan payments generally rise during the build when the loan uses interest-only payments based on the amount advanced and outstanding.
Key takeaways
- Construction funds are normally released after a completed milestone, draw request, inspection, document review, and approval.
- A draw inspection verifies reported progress against the budget and schedule; it is not a universal certification of workmanship or code compliance.
- California progress payments use distinct statutory conditional and unconditional waiver-and-release forms.
- General-contractor releases do not prove that every subcontractor or supplier has been paid.
- Retainage, title updates, permits, Notice of Completion procedures, and final-completion documents can affect the timing of the last draw.
- Renovation products can use different escrow, reimbursement, initial-advance, inspection, and completion rules than ground-up construction loans.
- Draw delays can increase interest carry and create builder cash-flow pressure.
Sources
- California Civil Code Section 8800, covering private-work progress payments, good-faith disputes, withholding limits, and retention: (leginfo.legislature.ca.gov)
- California Contractors State License Board guidance on conditional and unconditional waiver-and-release forms under Civil Code Sections 8132, 8134, 8136, and 8138: (cslb.ca.gov)
- California Contractors State License Board guidance on lien releases and Notices of Completion: (cslb.ca.gov)
- Fannie Mae HomeStyle Refresh requirements for initial renovation draws, completion deadlines, completion escrow, certification, and title updates: (selling-guide.fanniemae.com)
- Fannie Mae requirements for completion certification, final disbursement, title updates, and postponed-improvement escrows: (singlefamily.fanniemae.com)
- Fannie Mae guidance on completion reports and alternatives for verifying construction, repairs, and renovations: (singlefamily.fanniemae.com)
> Disclaimer: This article provides general educational information. The construction-loan agreement, construction contract, lender or servicer instructions, title requirements, applicable program guidelines, project documents, and advice from qualified California counsel control a specific transaction.
References
- https://files.consumerfinance.gov/f/documents/cfpb_trid-separate-construction-loan-guide.pdf
- https://dollar.bank/personal/borrowing/mortgages/building-a-home/closing-on-your-mortgage
- https://www.pillarprivatelending.com/resources/construction/construction-draw-process
- https://singlefamily.fanniemae.com/media/41596/display
FAQ
How long does a construction loan draw take after an inspection?
A draw is funded after the inspection, document review, and payment conditions are complete, with the actual timing established by the lender’s procedures and loan documents.
Should the borrower or contractor submit the draw request?
The borrower or contractor submits the draw request according to the lender’s written procedure, and the loan documents identify the responsible party.
What happens when a draw is rejected?
The lender identifies the missing work or documentation, and the borrower or contractor corrects the deficiency before resubmitting the supported amount.
Who pays construction inspection fees?
Inspection fees are charged according to the construction loan agreement, escrow instructions, or lender fee schedule.
Does retainage reduce every construction draw?
Retainage reduces a draw when the construction contract or loan documents authorize a holdback for later completion, punch-list work, or another stated condition.
Can a lender delay payment after the inspection is complete?
A lender can delay disbursement when required documents, title information, permits, lien releases, approvals, or other payment conditions remain incomplete.
Can a contractor receive funds before completing all work in a milestone?
A contractor receives a standard progress draw for the completed and documented portion supported by the inspection and loan documents, while an initial advance is available only when the applicable program and loan documents permit it.
Does every construction loan use the same draw process?
Every construction loan does not use the same draw process because lenders and renovation programs set different rules for inspections, reimbursements, escrow controls, payment recipients, documentation, and completion.
Do construction-loan payments rise during the build?
Construction-loan payments generally rise during the build when the loan uses interest-only payments based on the amount advanced and outstanding.